You prepare the accounts. We produce the evidence.
Market value evidence for the unlisted assets in your clients' funds. One valuation per asset, per year.
Units in an unlisted unit trust
Valuation Desk is the SMSF service of PM Vals, which values private credit and equity under IPEV, AASB 13 / IFRS 13 and AASB 9 / IFRS 9.
What the ATO actually requires.
Narrower than most trustees assume, and wider than a number in a spreadsheet.
Trustees must value all fund assets at market value when preparing the fund's financial statements, for 2012–13 and every year since.
Trustees must give the auditor all relevant, objective and supportable evidence to substantiate the valuation, on request.
The ATO states it is not the auditor's role to value fund assets or determine market value. They must obtain evidence, not create it.
No qualified independent valuer is required for a fund's accounts. The super laws only require one where a collectable or personal use asset is disposed of to a related party. Source: ATO, Guide to valuing SMSF assets, last updated 15 May 2026.
The ATO's test, and what we hand you against it.
A file that fails one of these comes back to your desk.
Pick the asset. See what we need.
Cash, listed securities and managed funds are easy to value. These are the ones that come back.
How we value it
From the assets held in the company and the price paid on acquisition, with the method and assumptions written out.
What we need
- Entity financials
- Share register
- Constitution
Watch for
Statements carrying assets at cost are unlikely to be sufficient evidence on their own.
How we value it
From the trust's underlying assets. Widely held trusts and managed funds use the manager's published exit price.
What we need
- Trust financials
- Unit register
- Trust deed
Watch for
A manager's number is a starting point, not evidence. We show the workings behind it.
How we value it
Against current rates and the borrower's position, with recoverability and any security recorded.
What we need
- Loan agreement
- Security docs
- Payment history
Watch for
Loans left at cost or par plus accrued interest are exactly what auditors query.
How we value it
Where property is the only asset, the entity value follows a property valuation you or the trustee supply.
What we need
- Entity financials
- Property valuation
- Deed or constitution
Watch for
We value the structure, not the bricks. We are not property valuers.
What comes back.
Pages from live engagements. Names, counterparties and commercial terms redacted.
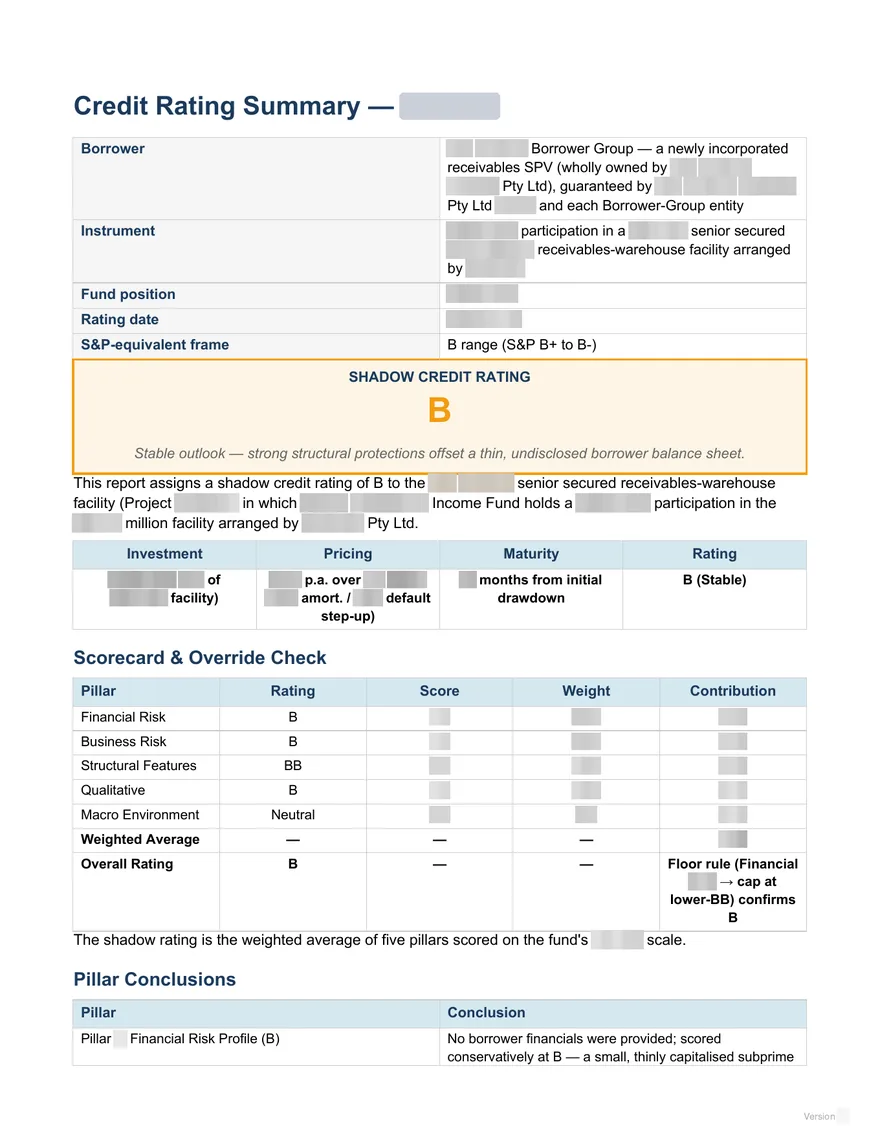
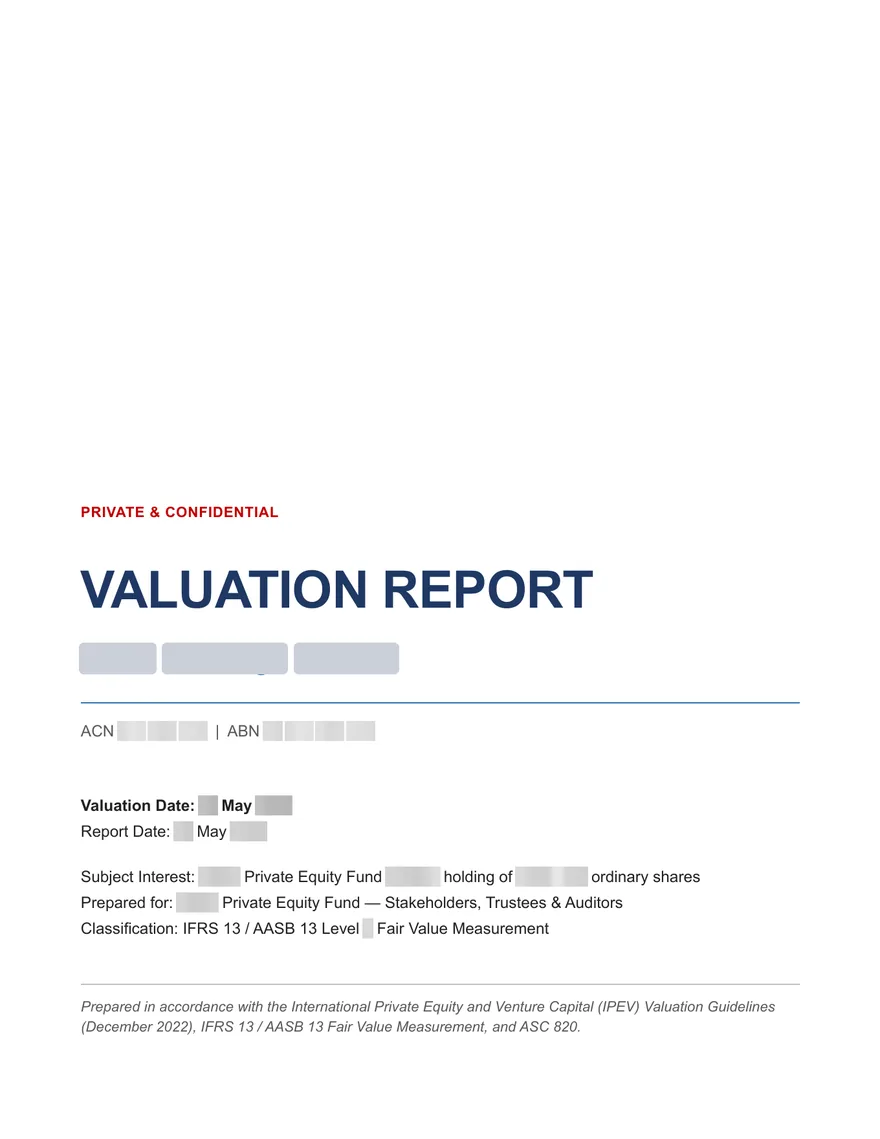
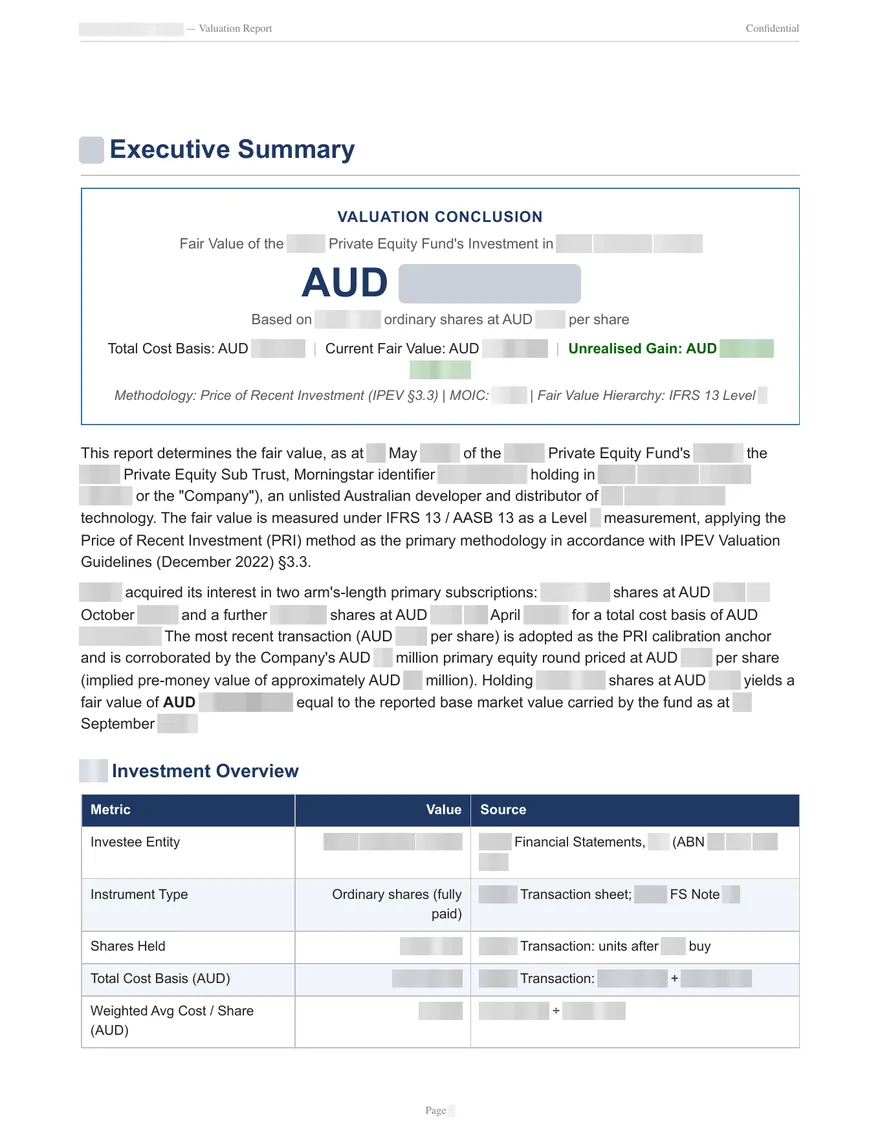
Per asset, per year, quoted up front.
No hourly billing. Volume across a book gets an engagement rate.
One asset, one annual valuation
One unlisted asset at the fund's year end, with the evidence file.
Per annual valuation
Incl. GST
- Market value at the fund's year end
- Method and assumptions written out
- Every input named, dated and sourced
- Evidence file for the audit
- Second reviewer before release
- We answer the auditor's questions on it
Fixed fee per asset. No hourly billing.
Send a list. Get the files back.
Start after year end and you'll have the files before the audits go out.
Send the asset list
The funds, the assets and the year end. One spreadsheet is enough to start.
Once per seasonWe collect what we need
Entity accounts, deeds, registers, loan agreements. We chase them, or take them if you hold them.
We do the chasingValued and reviewed
Market value from objective and supportable data, re-computed by a second reviewer.
Two sets of eyesFiles come back
One valuation and evidence file per asset, ready for the working papers.
PDF per assetQuestions practices ask.
Who engages you, us or the trustee?
Either. Most practices engage us directly and on-charge the fee; some refer the trustee and stay out of the billing. The file's the same either way.
Does the ATO require an independent valuer for this?
No, not for a fund's accounts. The super laws only require one where a collectable or personal use asset goes to a related party. What's required is objective and supportable data the auditor can see. The ATO does recommend an independent valuer where an asset is a big slice of the fund, or where the valuation is complex, which covers most unlisted holdings.
What actually happens if the evidence is not there?
The auditor considers modifying the independent auditor's report, and must lodge an auditor/actuary contravention report where values may be misstated and the reporting criteria are met. If they can't put a number on the contravention, the ATO tells them they may report the total asset value as its maximum. One thin holding can end up reported at its full carrying amount.
The fund holds units in a private credit fund. Is the manager's number enough?
Treat it as a starting point, not as evidence. ASIC's REP 820 found wholesale funds with no valuation policy at all, and funds revaluing only when a credit trigger fired. The ATO counts entity financial statements as reliable evidence only if they're signed, audited and carry assets at market value rather than cost.
Will our auditors accept it?
The auditor checks the valuation rather than performing it, and judges whether the basis suits the asset. We document the method, inputs, sources and dates, and we'll answer questions on our own file. We can't guarantee any particular auditor's conclusion.
Do you deal with our clients?
Only if you want us to. We can work through your team, or go to the trustee direct for the documents. Tell us which at the start and we'll stay inside it.
Does every fund need this every year?
All fund assets must be valued at market value each year. If you're leaning on a prior valuation, the trustee has to assess and document that it's still appropriate. In practice an unlisted holding needs fresh support most years.
What about the property and the listed portfolio?
Listed securities take the closing price at 30 June, and widely held trusts use the manager's published exit price. We don't value real property. The ATO also says one item of evidence is rarely enough on its own, and an agent appraisal that doesn't list the comparable sales behind it generally won't do.
What is the turnaround?
Set by how fast the entity accounts arrive, not by the valuation. Send the list early and we'll work through the book rather than queue behind October.
How is it priced?
$399 per asset for one annual valuation, including GST, agreed before work starts. Volume across a book gets an engagement rate.
Send us the fund you least want to explain.
One asset, one year end. We will tell you what we need and when you will have it.
ben@pmvals.comImportant information & disclaimers
General information only. This website describes Valuation Desk's services and summarises publicly available ATO guidance. Nothing here is financial product advice, investment, legal, tax or accounting advice, an offer, or a recommendation to buy, sell or hold any asset. It does not take account of any fund's objectives, financial situation or needs. Obtain your own independent advice before acting.
The trustee remains responsible. Valuing a fund's assets at market value is the trustee's obligation. We prepare a valuation and an evidence file to support it. The trustee must be satisfied the valuation is appropriate for the fund, adopt it, and make the evidence available to the fund's approved SMSF auditor. Engaging us does not transfer the trustee's obligations, or a practice's obligations to its own clients.
Sources. References to ATO requirements summarise the ATO's Guide to valuing SMSF assets (last updated 15 May 2026) and Verifying the market value of fund assets (last updated 2 April 2025). References to ASIC findings summarise REP 820 Private credit surveillance report: retail and wholesale funds (5 November 2025), which concerns private credit funds and not SMSFs directly. All are provided as general background, may change, and should be read in full against the fund's circumstances.
Not a qualified independent valuer engagement. A standard engagement is a valuation supported by an evidence file, not a valuation by a qualified independent valuer for the purposes of the superannuation regulations. Where the law requires a qualified independent valuer, being the disposal of certain collectables and personal use assets to a related party, a separate engagement with a specialist valuer is required. We do not value real property or chattels.
No guarantee of value, acceptance or outcome. A valuation is an independent opinion of market value at a point in time, based on the information supplied and the assumptions stated. It is not a guarantee of realisable value, a promise of future performance, or a transactable price. We do not guarantee that any auditor, the ATO or any other party will accept a valuation.
Illustrative material. The valuation docket shown on this page is illustrative. It is not live output or real client data.
Pricing. $399 per asset for one annual valuation, inclusive of GST. Fees are agreed before work begins and final scope is set in a written engagement. Complex assets, additional assets and out of scope work are quoted separately. Engagement rates for practices are agreed case by case.
Provider & liability. Valuation Desk is a service of PM Vals (Private Market Vals), a business name of Meek Private Equity Pty Ltd (ACN 670 079 759). To the maximum extent permitted by law, no liability is accepted for reliance on this website. Content may change without notice. © 2026 Meek Private Equity Pty Ltd.